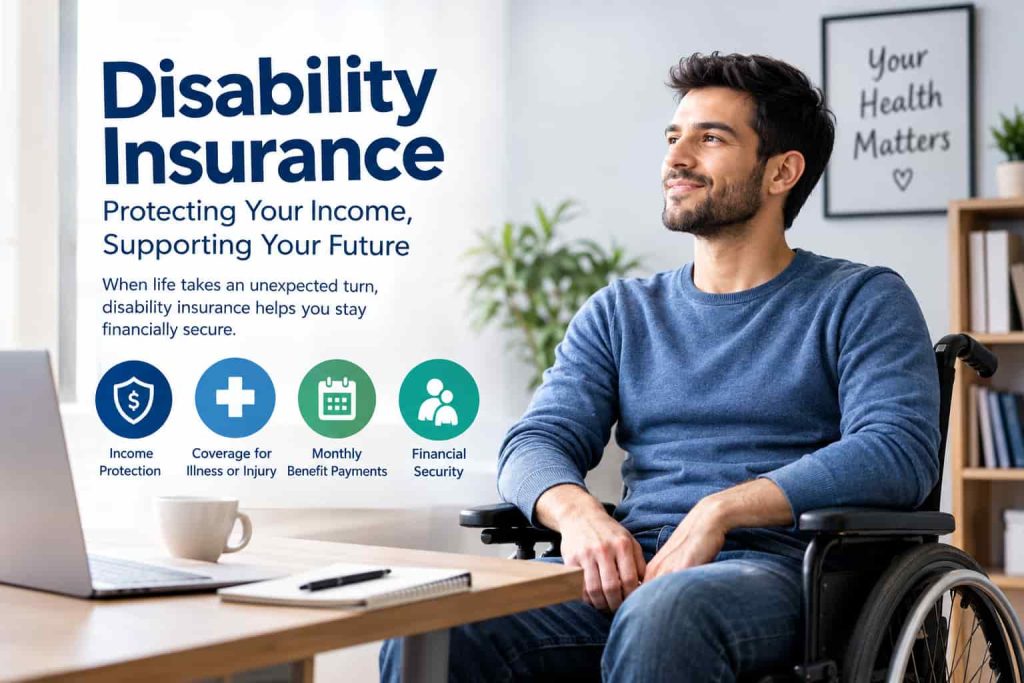
You have the power of a financial asset that can make you an income: you are yourself. When people start to think about insurance, they tend to think in terms of either Health Insurance, Auto Insurance, or Life Insurance, but many don’t consider protecting the paycheck on which they are relying to provide for their everyday needs. Disability Insurance can help replace a portion of your income, and take some of the financial strain out of an illness or injury that prevents you from working.
Studies indicate that not many people are aware of the prevalence of disabilities. The insurance industry and Social Security Administration have estimates that cite one in four workers could become disabled before retirement age. Disability insurance is a crucial component of financial planning because it can impact a variety of aspects, such as your housing, long-term financial goals and more, when your income is lost unexpectedly.
What Is Disability Insurance?
Disability Insurance is an income protection insurance to cover monthly income when an illness or disability renders the individual unable to work. The policy is not to pay your medical bills, but rather replaces some of your lost income so you can pay your bills. If you have a job, you are a freelancer, contractor, healthcare worker or a business owner, your money is essential in keeping your financial life on track. Disability coverage can help safeguard that income if an unanticipated health event impacts your ability to earn income.
Why Disability Insurance Matters
While many think that disabilities only occur when there’s a severe accident, there is a different story according to the statistics. Some of the most common types of disabilities are chronic illnesses, heart disease, cancer, neurological disorders, musculoskeletal issues and more. Anyone, irrespective of their profession or age can suffer from health problems.
Even if the worker can’t work for a short period, it can lead to economic stress if there is no income support measure in place. All bills and commitments for a mortgage, rent, groceries, utilities and more remain unchanged even if you’re sick. Disabled Insurance is an insurance that could help to financially support you during tough times.
How Disability Insurance Works
When you buy a disability insurance policy, you pay an insurance premium to keep it and your coverage in force. If the covered illness or injury makes it impossible to be able to perform his or her job duties, then the insurance company may pay him or her monthly benefits once the waiting period is over.
Typically disability insurance policies pay between 50% to 70% of your pre-disability income. This will depend on the policy and the amount of cover, the income and the benefit payout. Those payments may even assist you with essential living costs whilst you are concentrating on recuperating.
Short-Term vs Long-Term Disability Insurance
Short-Term Disability Insurance is meant for medical issues that are short-term. Services for recovery from surgery, injuries, pregnancy-related issues or short-term illnesses could be covered by these policies. Typically, coverage is for a few weeks or months as outlined in the plan.
Long-Term Disability Insurance is meant for the more serious conditions that may impact earning capacity for an extended period of time (years). While some policies may still be in effect up till retirement age or until you can get to work again. Long-term disability can be an integral part of a professional’s financial safety net for many.
Who Should Consider Disability Insurance?
Earned income always needs coverage, so if you rely on your income, it’s important to get disability insurance. If workers suddenly become unable to work, they will experience a financial loss regardless of their employment status.Losing a worker’s ability to work will result in a loss of income for workers, whether they are an employee, a freelancer, a consultant, an entrepreneur or self-employed.
Those who have an income responsibility, such as a mortgage, children, business commitments, education costs or other financial responsibilities are most likely to require income protection. A disability insurance plan may be an excellent means to protect your way of life and monetary future when times are uncertain.
What Does Disability Insurance Cover?
This coverage is subject to the type of insurance policy and insurance company. If you get sick with a covered illness or injury that means that you can’t perform the duties associated with your occupation, then this may give you the right to disability benefits. Certain medical conditions, such as cancer treatment, a severe back injury, recovering from a stroke, heart disease, neurological disease or other qualifying medical conditions may be covered. All policies have conditions of benefit, waiting periods, exclusions and definitions. Those details can help you determine the coverage you need that will reflect your profession, income and finances.
Benefits of Disability Insurance
One of the greatest benefits of disability insurance is that it pays you your income. Monthly benefits can assist you to make sure that you can continue paying your essentials without having to use all of your savings, loans or credit cards. There are no magic bullets when it comes to financial responsibilities during a recovery, so it’s particularly beneficial to have a source of income available.
Disability coverage can also help to provide financial security in the long-term. While having a temporary or longer disability might not mean you don’t earn an income, you can better protect your retirement savings, investments, education plans and your household’s stability.
Disability Insurance vs Life Insurance
Often disability insurance is discussed with life insurance as both insure someone’s finances. Life insurance is a kind of insurance that gives financial assistance to the beneficiaries after the insured person’s death and disability insurance provides assistance during one’s lifetime if he/she becomes unable to work. Many financial advisors will not opt for one or the other, but consider both policies to be a part of a protection plan. They, along with Health Insurance, provide greater financial security for you and your family.
How to Choose the Right Disability Insurance Policy
Comparing premiums isn’t the only factor to consider when selecting a disability insurance policy. Once you have looked at the different options, coverage limits, benefit periods, waiting periods, occupation definitions and the reputation of the insurance company all contribute to your evaluation of the various options.
Whether you’re buying coverage, you need to think about your monthly bills, storing up emergency money, your existing employee advantages and future monetary obligations. If a policy includes income replacement it should offer sufficient income to keep you financially stable without putting an undue strain on your finances.
Disability Insurance and Financial Security
There are reasons for government and insurance bodies to continue monitoring the trend of disability on a State level, as this has a direct impact on the workforce participation and household income. A disability can cause a family or a person to experience financial difficulties over an extended period, when they suddenly aren’t earning an income.
It’s important to keep earning power as well as physically valued assets safe. Having disability insurance can allow you to have a financial buffer that can help alleviate some of the uncertainties and give you some peace of mind during challenging times.
Conclusion
Disability Insurance is among the most crucial types of income protection which are available nowadays. Relationships with your ability to earn an income support most, if not all, financial goals, ranging from the monthly bill payments to future financial security. If you have a disability insurance policy properly designed, it can offer you good financial support if you fall ill or injured, and can no longer work. Disability insurance can be important for everyone from employees to freelance workers, entrepreneurs to business owners as they prepare their financial future and make informed financial decisions.
Frequently Asked Questions
What is Disability Insurance?
Disability Insurance is a type of income protection insurance that will provide partial benefits when a disability, such as illness, injury or medical condition, prevents you from working. The aim is to contribute to the financial stability in recovery.
Does employers’ Disability Insurance cover the needs?
Employer-sponsored coverage can be a good option, but may have limits on coverage and restrictions on coverage. Those with extra private disability insurance may opt to have it for additional coverage.
Why should Disability Insurance be of importance?
Disability Insurance can help maintain your income, financial security and prevent you from running out of savings because of a health condition that prevents you from working.